
What is a brokerage channel?
Wondering what a brokerage channel is? Definition, how it works, legal framework, and a real-life example.

In short
6 min read
The brokerage channel is a method of insurance distribution where the company operates through independent brokers, representing approximately 18% in P&C insurance and 13% in life & health insurance in France.
The broker advises and compares offers for the client, while the company designs the products and manages the risk, within a framework regulated by ORIAS and ACPR.
This channel benefits insurers (broader market access), clients (independence and competition), and sales representatives (a profession focused on managing a network of brokers).
The brokerage channel refers to a distribution method for insurance products in which the company works through independent brokers rather than selling directly. It is one of the major distribution channels in the sector, alongside direct sales and exclusive agents.
In France, brokerage accounts for approximately 18% of property and casualty insurance and around 13% of personal insurance. According to sector analyses, its share is, however, much higher in professional markets, where it becomes the dominant channel for complex risks (construction, industrial risks, professional liability).
This article aims to simply explain what the brokerage channel is, how it works, and what it practically changes. Whether you are a client looking to understand the benefit of using a broker, or an insurance sales representative wanting to grasp your role in this network, this article is for you.
The Brokerage Channel
A brokerage channel is a distribution network in which brokers offer their clients the products of one or more insurance companies. The company does not sell directly: it relies on these intermediaries to find clients, analyze their needs, propose solutions, and manage the commercial relationship.

It is therefore not a specific company, but rather a way of distributing policies.
Brokerage Versus Other Channels
To fully understand the specifics of brokerage, the easiest way is to compare it to the other two major distribution channels in insurance:
Direct Sales
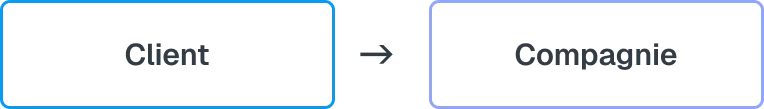
The company sells directly to the client without an intermediary: website, call center, or salaried branch.
The Exclusive Agent Channel
The exclusive agent most often represents a single company, whose products they distribute.

The Brokerage Channel
The broker, on the other hand, remains independent and can work with several companies at once.
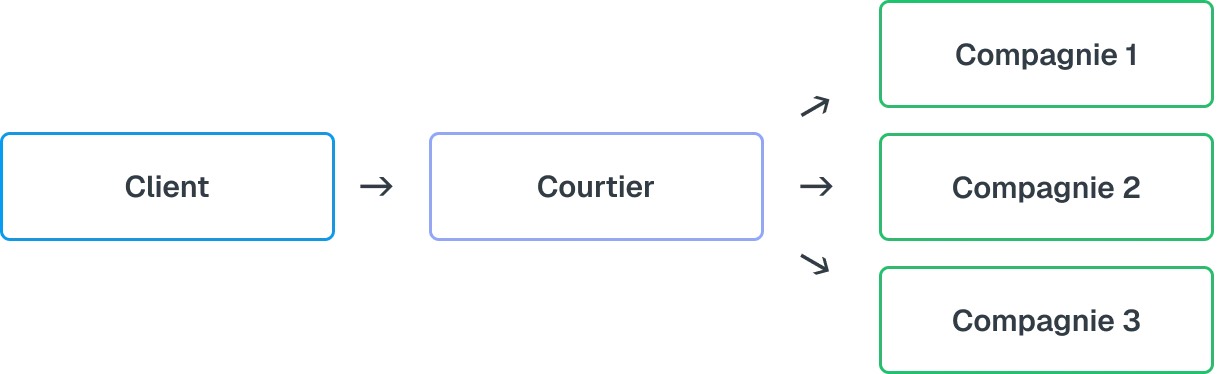
It is this independence and the ability to compare multiple insurers that fundamentally distinguishes brokerage from other channels.
How Does the Brokerage Channel Work?
Now that the place of brokerage is established, let's see who plays what role.
The broker advises the client, compares market offers, selects an appropriate solution, and manages the relationship. They are one of the many insurance players involved between the policyholder and the company. In return, they are compensated, most often through a commission paid by the insurer, and sometimes through fees billed directly to the client.
The company, on its part, designs the products, accepts or rejects the risk, sets the pricing, and manages claims payouts.
In practice, a broker might, for example, put multiple insurers in competition for a business exposed to industrial risks (fire, business interruption, public liability). Each insurer then proposes a different price and level of coverage, which the broker compares before recommending a single solution to their client.
Thus, everyone keeps their role: the broker is the customer relationship expert, the company is the risk expert.
Why Do Companies Use Brokerage?
From the insurer's perspective, this channel offers several benefits:
accessing a broad sales network without having to recruit massively,
reaching specialized markets that are difficult to target directly,
benefiting from an extended geographic presence, an essential driver of insurers' territorial development.
The second benefit is often decisive. For industrial risks, construction, or cyber insurance, coverage needs are too specialized to be handled effectively directly: this is where the broker brings the expert knowledge that makes the difference. This explains why many niches (businesses, complex risks, specific professions) primarily use brokerage.
🚨 The insurance intermediation market is highly fragmented: there are nearly 62,000 registered intermediaries in France (ORIAS, 2024), including nearly 27,000 brokers representing a significant portion, alongside exclusive agents and representatives. This fragmentation partly explains the sector's high dependence on structured brokerage and distribution networks.
Client Side: Why Use a Broker?
For the client, brokerage meets a simple need: to be well-advised without having to contact every insurer themselves. Specifically, the broker provides:
independence, as they are not tied to a single company,
market evaluation of multiple insurers to find the best coverage-to-price ratio,
personalized advice tailored to the client's actual situation,
and assistance during a claim, where they often act as the intermediary with the company.
This is where the real added value of the channel lies for both individuals and businesses. In commercial insurance, this long-term relationship also makes it possible to identify new needs and offer additional coverages. This is notably the principle of cross-selling in B2B insurance.
Sales Side: What's the Job in Brokerage?
For an insurance sales representative, the brokerage channel shifts the very nature of the job. A representative working for the company does not sell directly to the end client: they do indirect sales.
Their role consists of:
managing a network of partner brokers,
developing relationships and building new partnerships,
training brokers on the company's products,
helping them close more deals.
In short, their customer is the broker, not the policyholder. This is an essential distinction for anyone starting in this channel.
Managing this network is not something you do on the fly: identifying high-potential brokers and tracking partner activity requires a systematic approach. That is why many insurers now rely on sales intelligence tools to identify growth opportunities and steer their distribution.
The Regulatory Framework
Brokerage is a regulated activity, which protects the client and structures the profession. Three key markers to know:
ORIAS: every broker must be registered in this official database of insurance intermediaries,
ACPR (Prudential Supervision and Resolution Authority): it supervises the activity,
the duty to advise, arising from the Insurance Distribution Directive (IDD): the broker must recommend a solution that is genuinely suited to the client's needs and justify it.
For the client, it is a guarantee; for the sales rep, it is the framework within which all distribution takes place.
Difference Between Network, Wholesaler, MGA, and Delegation
Several concepts revolve around the brokerage channel and are often mixed up. Here is how to distinguish them.
The Brokerage Network
This refers to a structured organization of brokers working together (group of firms, franchise, platform). The goal: pool resources, negotiate together with insurers, and share tools.
The Wholesaler
This player occupies an intermediate position between the insurer and the retail brokers. They design specific products, negotiate terms with the companies, and then redistribute these offers to a network of brokers. They are generally not in direct contact with the end client, and they are particularly useful in niche markets.
The MGA (Managing General Agent)
This is close to a wholesaler, but with more authority. They receive a delegation from the company to underwrite policies, set certain terms, and accept or reject risks. They can be seen as a delegated "mini-company," very active in complex risks.
Underwriting Delegation
This is not a player but a mechanism: the company gives an intermediary (an MGA, sometimes a wholesaler) the right to analyze the risk, decide whether to accept it, and issue the contract. This speeds up distribution without having to go back to headquarters for every file.
Summary Table of Different Networks
Concept | In One Sentence | Diagram Header |
|---|---|---|
Brokerage channel | A distribution method | Company → Brokers → Clients |
Brokerage network | An organization of brokers together | Grouped brokers → Companies |
Wholesaler | An intermediary structuring the offer | Company → Wholesaler → Brokers |
MGA | A wholesaler with underwriting authority | Company → MGA (decides) → Brokers |
Underwriting delegation | Authority granted to an intermediary | Company → delegates decision |
Concrete Example: Albingia, a 100% Brokerage Insurer
The best example is undoubtedly Albingia, an independent French insurance company specializing in corporate risks. Its model is clear-cut: it distributes its solutions exclusively through brokerage, with no direct sales to the end customer.
In practice, Albingia relies on a network of over 5,000 active brokers, whom it manages from its headquarters and its seven regional branches. Construction is furthermore its primary line of business: it has supported developers since the introduction of compulsory construction insurance. And since it only targets professionals, with no branch network, brokerage is its sole distribution channel.
The model works: in 2024, Albingia recorded €347M in net earned premiums (up about 4% year on year) and a net income of €52.7M.
This is the perfect illustration of how a company can conquer a technical market by relying entirely on specialized brokers instead of its own branches.
Sources: Albingia, Integrated Report 2024; L'Argus de l'assurance.
The brokerage channel is therefore a distribution method built on independence and advice. For the client, it opens up access to multiple insurers and tailored guidance; for the sales rep, it defines a career oriented around network management rather than direct sales.
What is the difference between a broker and an exclusive agent?
Is using a broker more expensive?
What is a wholesale broker?
Is a broker truly independent?
Taina left her position as Area Manager at AB InBev for marketing and communications, a true career choice. Having experienced the reality of the sales force from the inside, she writes about the profession without ever distorting it. She doesn't just talk about the field; she comes from it. Outside the office, she tracks down the best tables in town: finding the right spot is a serious business.
See also

Artificial intelligence and field professions: what our 2026 studies reveal
Adoption, barriers, use cases: discover what our three studies reveal about the role of AI among sector managers, sales representatives, and foodservice sales reps.

CHR and RHF Sales Representatives: portrait of a relationship-driven profession in the era of data
Equipment, productivity, AI: discover the major trends for the HORECA and food service sales profession in 2026 through our field study.

Pharmaceutical Sales Representative in France: Portrait of a Field Job Under Pressure
Compensation, aspirations, AI usage: discover the major trends in the pharmaceutical sales representative profession in 2026 through our field study.

Area Sales Managers in France: who are they and how is the profession evolving in 2026?
Compensation, aspirations, AI usage: discover the major trends in the field sales representative profession in 2026 through our field study.
The area manager professions in 2026
Discover the trends, the challenges, and the key figures.